
Protecting the Bottom Line: A Practical Framework for Eliminating Systemic Margin Leakage
Margin protection has become a defining priority for manufacturing and retail executives across the United States and Europe. With elevated capital costs, tighter lending conditions, and demand volatility becoming normal rather than exceptional, sustainable profitability depends on operational precision. In many mid-sized organizations, margin erosion does not originate from a major strategic error; it develops gradually through minor system misalignments, inconsistent data governance, and manual processes that appear manageable when viewed individually. Inventory variances, order corrections, spreadsheet-based planning adjustments, and recurring reconciliation work compound over time. When aggregated, these routine inefficiencies create measurable structural drag. The opportunity for leadership is not wholesale system replacement but disciplined alignment across ERP, WMS, MES, POS, EDI, forecasting, and BI reporting environments so that existing infrastructure consistently supports margin protection.
For organizations with 10–100 employees and $10M–$500M in revenue, particularly those operating multiple facilities or distribution nodes, system complexity often increases incrementally. Each acquisition, new channel, warehouse expansion, or product line extension introduces additional synchronization requirements. Teams frequently compensate through manual oversight and practical workarounds. While this flexibility demonstrates operational strength, reliance on manual controls eventually impacts working capital efficiency and forecast confidence. The objective is not technical perfection; it is measurable control, financial clarity, and operational alignment.
ERP and WMS Alignment: Protecting Inventory Accuracy and Working Capital
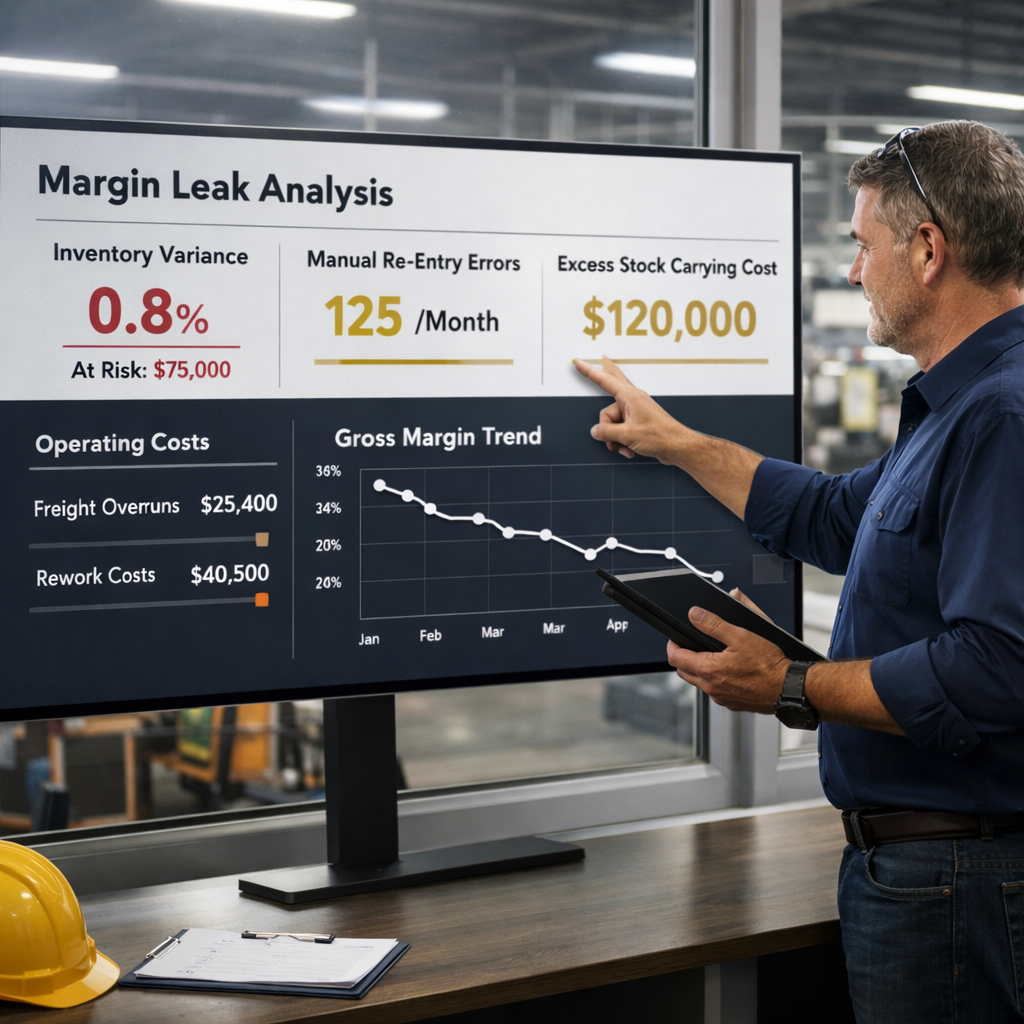
The integration between ERP and WMS directly influences inventory accuracy, production continuity, and working capital performance. Even small synchronization gaps can generate disproportionate financial impact. For example, a 0.75% variance on a $20M inventory base represents $150,000 in exposure. If only half of that variance becomes realized through write-offs, expedited freight, or production delays, the annual margin effect remains approximately $75,000. Secondary effects are defensive purchasing, inflated safety stock, and reduced MRP reliability , further compound the issue.
Common indicators of ERP and WMS misalignment include:
- Repeated manual inventory reconciliations outside standard cycle counting
- Frequent adjustments between book and physical inventory
- MRP recommendations overridden due to low confidence in quantities
- Month-end close delays caused by inventory validation reviews
Financial implications extend beyond write-offs. A modest 2–3% increase in safety stock on a $20M inventory base ties up $400,000–$600,000 in additional capital. At a conservative 20% carrying cost, this equals $80,000–$120,000 in annual expense. Strengthening ERP–WMS synchronization through real-time transaction posting, automated variance alerts, structured cycle counting governance, and executive-level review of variance metrics can significantly improve inventory control without replacing core systems. This approach reinforces working capital discipline while preserving operational stability.
Reducing Manual Order Entry and Freight Leakage
Manual order re-keying between EDI feeds, eCommerce platforms, POS systems, and ERP environments remains common in mid-sized companies. While manual review may provide perceived oversight, it introduces recurring risk and labor inefficiency. In many environments, cross-functional correction efforts consume 10–15 hours per month, representing $10,000–$15,000 in annual capacity cost. If preventable routing or data entry errors create a 1% freight premium on a $2.5M freight budget, the resulting annual expense approaches $25,000. Combined direct impact frequently reaches $35,000–$40,000 per year.
Additional operational consequences may include:
- Delayed invoicing and extended Days Sales Outstanding (DSO)
- Increased credit memo volume due to pricing discrepancies
- Customer service escalation tied to fulfillment errors
- Finance workload related to dispute resolution
Automation should be implemented with structured controls rather than full elimination of oversight. A balanced model includes:
- Direct EDI-to-ERP integration with validation rules
- Automated logging and exception alerts
- Threshold-based review for high-risk or high-value transactions
- Periodic audit sampling to ensure integrity
This controlled integration reduces error frequency, accelerates the order-to-cash cycle, and improves customer satisfaction while maintaining governance visibility.
Forecast Accuracy, Spreadsheet Dependency, and Excess Inventory
When operational teams rely on spreadsheets instead of ERP-based forecasting or MRP outputs, it often signals low confidence in system data. Inconsistent lead times, outdated Bills of Materials (BOMs), or misaligned inventory balances typically drive this behavior. A modest 3% excess inventory position on a $20M base equals $600,000 in additional stock. At a 20% carrying cost, that represents $120,000 in annual margin drag.
Beyond financial impact, spreadsheet-based planning introduces structural risks:
- Data latency of 48–72 hours behind transactional systems
- Key-person dependency tied to locally maintained files
- Limited audit trails for forecast overrides
- Reduced cross-site visibility in multi-location operations
Improving alignment between ERP forecasting, MES production reporting, and WMS inventory balances increases transparency and reduces unnecessary buffer stock. It is important to recognize that improved system integration does not eliminate demand variability. It does, however, remove preventable distortion so leadership decisions are based on accurate, current information rather than manually adjusted approximations.
Master Data Governance and Gross Margin Protection
Master data consistency across ERP, MES, POS, and planning systems is a direct determinant of gross margin integrity. When cost updates in ERP fail to propagate to MES, outdated BOMs remain active in production, or pricing discrepancies exist between POS and ERP, margin reporting becomes distorted. Even a 0.2%–0.5% margin shift is financially material. In a $50M organization, a 0.5% distortion equals $250,000.
Operational effects of weak master data governance may include:
- Scrap and rework from incorrect BOM configurations
- Inaccurate OEE reporting due to flawed production standards
- Customer invoice disputes linked to inconsistent pricing tables
- Misleading BI dashboards that inform executive decisions
Effective governance requires clearly defined ownership and accountability. Recommended practices include:
- Named data owners for item master, cost standards, pricing tables, and supplier data
- Formal change approval workflows with documented impact assessment
- Quarterly validation audits for high-impact data fields
- Integration testing protocols before production updates
This structured discipline ensures that executive reporting reflects operational reality and that strategic investments are grounded in accurate margin data.
Operational Risk, Audit Integrity, and Cyber Exposure
Temporary solutions such as shared spreadsheets, email-based approvals, side databases, and manual reconciliations often originate from practical necessity. Over time, however, these solutions become embedded in daily operations. As revenue grows and transaction volumes increase, oversight becomes more complex and audit trails fragment.
Risks associated with unmanaged workarounds include:
- Reduced fraud detection visibility
- Increased audit preparation complexity
- Expanded cybersecurity attack surface
- Inconsistent segregation of duties
- Difficulty tracing data lineage across systems
Mitigation strategies can be implemented without large-scale disruption:
- Eliminate duplicate data entry points wherever feasible
- Encrypt system-to-system data transfers
- Monitor integration logs and review exceptions monthly
- Separate data change authority from approval authority
- Maintain documented rollback procedures for integration updates
By viewing system governance as an extension of financial control, organizations strengthen both resilience and profitability.
ROI Mini-Model: Conservative Mid-Sized Example
Consider a $50M manufacturing organization with the following annual impact estimates:
- Inventory variance realization: $75,000
- Excess inventory carrying cost: $120,000
- Order and freight inefficiency: $40,000
- Finance reconciliation capacity drag: $70,000
Estimated structural margin impact: approximately $305,000 per year
If structured ERP, WMS, MES, and EDI integration improvements require an investment of $175,000 over 12 months:
- Payback period: less than 12 months
- Year two onward: $300,000+ annual retained value
- Five-year cumulative impact: exceeding $1.5M
This conservative model excludes softer benefits such as faster monthly close cycles, improved audit readiness, enhanced forecast confidence, and stronger executive reporting reliability.
A Phased Framework for Sustainable Margin Protection
A structured, phased execution model allows improvement without operational disruption:
Phase 1: Diagnostic and Quantification
- Audit duplicate data entry zones
- Measure inventory variance rates
- Quantify manual correction frequency
- Calculate excess inventory carrying cost
Phase 2: High-Impact Integration
- Strengthen ERP–WMS synchronization
- Automate EDI-to-ERP order intake
- Align MES production reporting with ERP cost structures
Phase 3: Governance and Metrics
- Formalize master data ownership
- Establish integration monitoring routines
- Track forecast accuracy and system integrity metrics
- Review results monthly at the executive level
This phased approach reinforces accountability across finance, operations, and IT while delivering measurable ROI.
What This Framework Does Not Solve
It is important to define scope clearly. Improved ERP alignment and system governance do not eliminate supplier disruptions, macroeconomic shifts, or demand volatility. They do not guarantee perfect forecasts or zero inventory write-offs. Instead, they reduce preventable inefficiencies, improve working capital control, and enhance leadership confidence in operational data. The goal is disciplined margin protection supported by reliable systems.
Leadership Perspective: System Discipline as a Strategic Asset
Revenue growth depends on market conditions. System discipline depends on management decisions. Organizations that treat ERP integration, WMS synchronization, MES accuracy, forecasting alignment, and master data governance as strategic financial levers consistently strengthen profitability and resilience. Reducing $250,000–$300,000 in annual structural drag compounds meaningfully over time and improves valuation, liquidity, and operational stability.
Achieving this level of alignment requires cross-functional coordination, phased execution, and clear ownership of outcomes. In many mid-sized companies, success depends on senior operational technology leadership capable of translating system architecture into measurable financial results while maintaining pragmatic execution discipline. The emphasis remains on governing and optimizing existing systems rather than replacing them.