
The Technology Roadmap Investors Actually Want to See
Most technology roadmaps built for an investor audience get the reader wrong before a single line item is drafted. I have reviewed dozens of these documents ahead of fundraising conversations, and the pattern repeats with striking consistency. The roadmap reads like an internal sprint board, full of features, dates, and story points, organised the way an engineering team would organise its own backlog. That structure makes sense for a stand up. It does not make sense for an investor, and using it in a pitch deck quietly signals something the founder never intended.
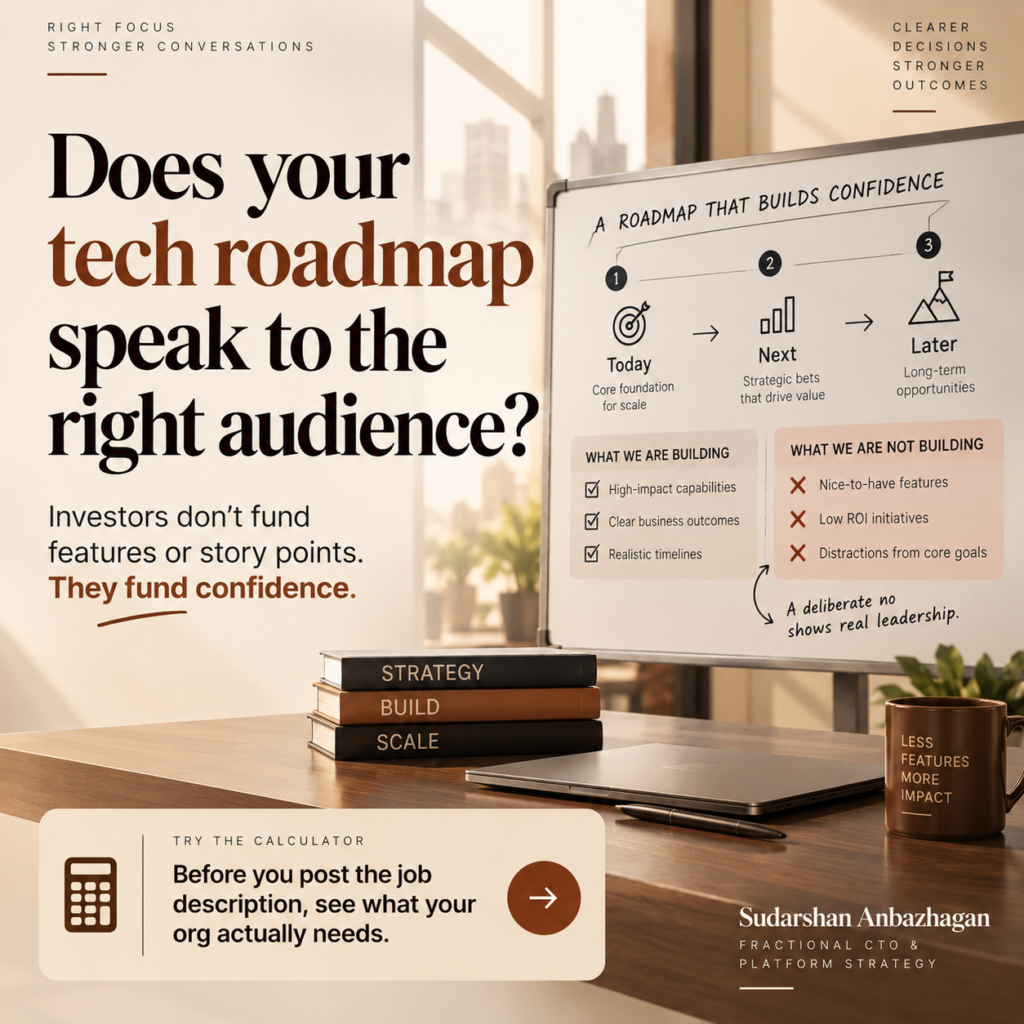
Investors do not fund story points. In my experience advising founders through fractional CTO engagements ahead of raises across the US, UK, and Europe, investors fund confidence that a leadership team knows which bets actually matter and, just as importantly, which ones they have deliberately chosen not to make yet. A roadmap dense with detail can look impressive on the surface while communicating the opposite of what a technical investor is actually screening for.
I have sat in enough of these conversations now to recognise the pattern instantly. The roadmap that gets the strongest reaction in the room is rarely the most detailed one. It is the one that clearly shows what the team chose not to build, and states plainly why that choice was made.
Why Investors Read Restraint as a Signal of Strength
A technology roadmap for investors serves a fundamentally different purpose than an internal roadmap. An internal roadmap coordinates a team around near term execution. An investor facing roadmap answers a much narrower question. Does this leadership team understand where the real technical risk sits, and are they allocating scarce engineering time toward the decisions that actually determine whether the business scales or stalls.
When a founder shows an investor a roadmap listing forty features across the next eighteen months with no visible prioritisation logic, the investor cannot easily tell which of those forty features the team believes is actually load bearing for the business model. Every item looks equally important because none of them has been marked as deliberately deprioritised. This absence of visible trade off reasoning is what makes an otherwise competent roadmap read as unconvincing to an experienced technical investor.
That single addition, the deliberate no, signals more technical leadership than a hundred line items ever will.
The opposite approach, where a founder explicitly states what the team chose not to build this year and explains the reasoning, does something valuable in the room. It demonstrates that engineering capacity is being treated as the finite, valuable resource it actually is, rather than as an unlimited pool that will eventually get around to everything. Investors who have sat through hundreds of pitches recognise this distinction immediately, because it mirrors exactly how they evaluate capital allocation decisions in every other part of the business.
The One Sentence Deliberate No Test
I use a simple diagnostic with every founder I advise ahead of an investor conversation, and it takes less than a minute to apply. If an investor asked what your team deliberately chose not to build this year, could you answer in one clear sentence. Founders who can answer immediately, with a specific example and a clear reason, are almost always founders who have done the harder work of genuinely prioritising their roadmap rather than simply listing everything the team hopes to eventually ship.
Founders who struggle with this question, hesitating or offering a vague answer about capacity constraints in general, usually have a roadmap problem that a slide redesign will not fix. The issue is not presentation. It is that the underlying prioritisation work has not actually happened yet, and no amount of formatting polish on the roadmap slide will hide that gap from an investor who has seen hundreds of these documents before.
| Sprint Board Style Roadmap | Investor Facing Roadmap |
|---|---|
| Lists every planned feature with dates | Names two or three bets that determine the business outcome |
| Treats all items as equally prioritised | States explicitly what was deliberately deprioritised, and why |
| Measures progress in story points and sprints | Measures progress in business outcomes the technology unlocks |
| Assumes unlimited future engineering capacity | Treats engineering capacity as a scarce, allocated resource |
Building the Roadmap Around Three Bets, Not Thirty Features
The most effective investor facing roadmaps I have helped founders build over the past several years share a consistent structure, regardless of the industry or the specific technology involved. They organise around no more than three strategic technical bets for the coming year, each one tied directly to a business outcome an investor already cares about, whether that is unit economics, retention, or the ability to serve a new market segment.
Each bet gets a short, plain language explanation of the assumption it rests on, the risk if that assumption turns out to be wrong, and what specifically would need to be true for the team to change course. This is a structure borrowed directly from how I build architecture decision records inside engineering organisations, applied instead to the investor conversation. The parallel is not accidental. Both documents exist to make an underlying assumption visible and falsifiable, rather than leaving it buried inside a list of tasks that nobody has connected back to why the business needs them.
Everything that does not fit inside one of these three bets still exists in the roadmap, of course, because the engineering team still needs a working backlog to execute against day to day. It simply does not need to be presented to an investor, because an investor is not evaluating the completeness of your backlog. They are evaluating whether your leadership team can distinguish between what is strategically load bearing and what is merely useful.
Before you post the job description, run the calculator and see what your organisation actually needs.
→ Calculate Your Fractional CTO ROI
→ Read the Fractional CTO Guide
What This Looked Like Ahead of a Recent Series A
A founder I advised ahead of a Series A raise came to me with a roadmap slide listing twenty two items across the next twelve months, organised loosely by quarter. Nothing on the slide was wrong exactly, but nothing on it told an investor which of those twenty two items the founder would protect if engineering capacity were suddenly cut in half. We spent one working session rebuilding the slide around three bets. A migration to support a new enterprise data residency requirement that was already blocking two deals in the pipeline. A rebuild of the onboarding flow tied directly to activation numbers the investor deck already highlighted. And a deliberate decision not to build a mobile application that year, despite repeated customer requests, because the data showed engagement happening almost entirely on desktop during working hours.
That third item, the deliberate no on mobile, generated more investor questions in the actual meeting than any of the features the team was building. Two separate investors independently told the founder afterward that the mobile decision was the moment they became confident the founder understood their own business model rather than simply reacting to the loudest customer request in their inbox. The raise closed within the timeline the founder had targeted, and the roadmap slide itself became something the founder reused, updated, in every subsequent board meeting.
Why This Matters More at Series A Than at Seed
The deliberate no test matters at every stage, but it carries particular weight at Series A and beyond, once an investor is evaluating not just the idea but the leadership team’s ability to allocate a scarce resource under real constraints. At seed stage, investors are often betting primarily on the founder and the market opportunity, and a slightly unfocused roadmap is more forgivable because the product itself is still finding its shape. By Series A, the questions get sharper. The investor has usually already seen the metrics, and the roadmap conversation becomes less about whether the idea works and more about whether the team can be trusted to spend the next round of capital with discipline.
This is exactly why the roadmap document deserves the same rigour a founder would put into a financial model before a raise. Nobody would walk into a Series A conversation with an unreviewed financial model, yet I regularly see founders walk in with a roadmap slide that has never been stress tested against the one sentence deliberate no question. Technical investors, and increasingly generalist investors who have learned to ask sharper technical questions, treat the roadmap as a proxy for how the founder thinks about trade offs everywhere else in the business, not just in engineering.
What to Ask Before Your Next Fundraising Conversation
If you are preparing for an investor conversation in the coming months, the most useful exercise is not polishing your existing roadmap slide. It is asking your own leadership team the deliberate no question before an investor ever gets the chance to ask it. What did we choose not to build this year, and can everyone in this room state the reason in one sentence without checking notes.
This discipline connects to the broader principle I describe in our piece on the GCC maturity model, where the organisations that mature fastest are consistently the ones willing to name what they are not doing yet, rather than presenting an undifferentiated list of everything technically possible. A roadmap built around three defensible bets, with the trade offs made visible, will earn more investor confidence than a roadmap built around thirty features nobody has prioritised against each other.
If an investor asked what you deliberately chose not to build this year, could you answer in one sentence.
Before you post the job description, run the calculator and see what your organisation actually needs.
→ Calculate Your Fractional CTO ROI
→ Read the Fractional CTO Guide